HOLIDAY BANK – FINANCE 2026: When Experience Becomes the New Competitive Advantage in Banking and Finance
The holiday season has always been a highly competitive “race” for the Bank – Finance sector, with countless offers competing for customer attention at the same time. As cashback and vouchers are no longer enough to create differentiation, the advantage now lies in understanding the right needs, showing up at the right moment, and delivering a seamless experience. Holiday 2026 therefore marks a shift from Promotion-led Campaign to Experience-led Financial Journey, where every financial touchpoint not only drives transactions but also becomes a useful and memorable part of the customer journey.
I. THE CONTEXT
Finance meets everyday life
1. Market context
The holiday season is a peak period for the Bank – Finance sector, when banks, e-wallets, and fintech brands simultaneously launch cashback, vouchers, card offers, and other demand-stimulation programs. However, as promotions increasingly become a market standard, while fast payments, eKYC, QR Payment, and Mobile Banking become more common, the gap in products and features between brands is also narrowing.
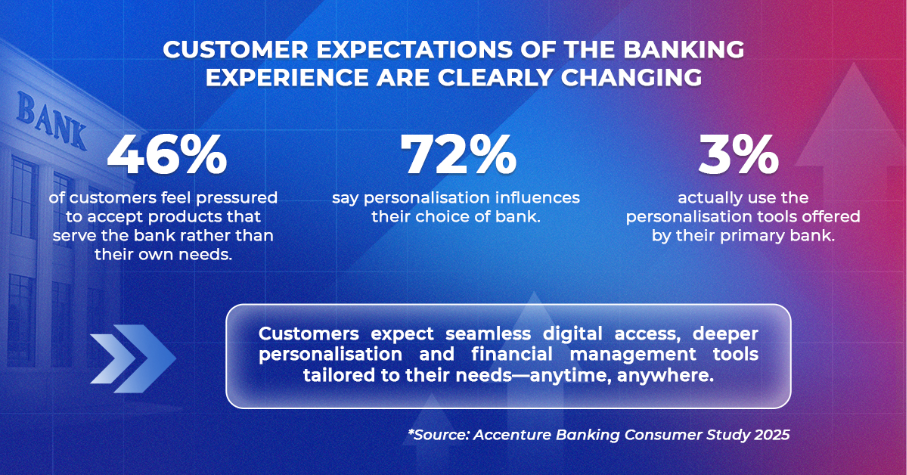
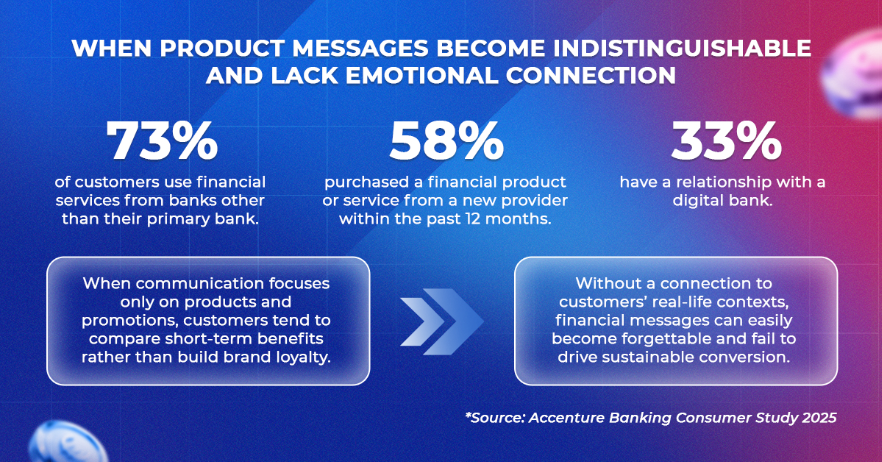
In this context, competition is no longer only about the size of an offer or the number of transactions. It increasingly depends on how well a brand understands customer needs and delivers the right value at the right moment. Accenture’s Banking Consumer Study, conducted with 49,300 customers across 39 countries, found that 73% use banks beyond their primary bank, while 58% purchased a financial product from a new provider in the previous 12 months; personalization is also an important driver of customer advocacy. Brands therefore need to understand not only who their customers are, but what they need at each moment.
2. Customer behavior
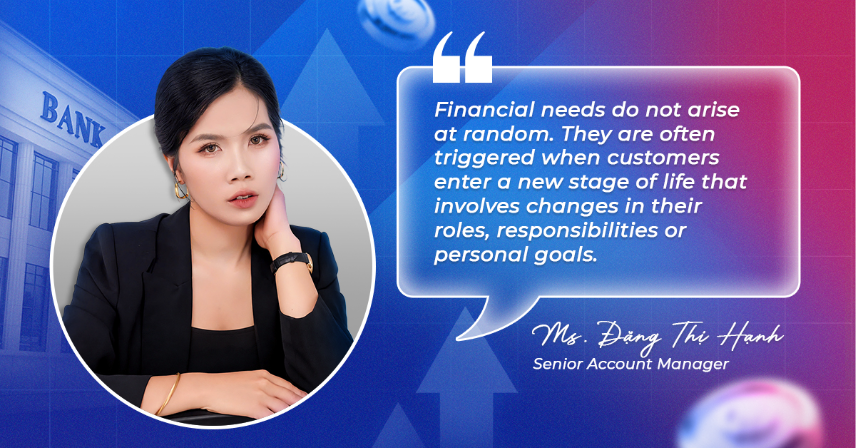
Users are increasingly less likely to begin with a need to open a card or take out a loan. Instead, they start with real-life goals such as shopping, travel, dining, entertainment, or family needs. According to Mastercard, 70% of APAC consumers are already using or want an all-in-one app that connects payments, shopping, and multiple services; in Vietnam, 56% have purchased through a social or messaging app.
Financial decisions are therefore increasingly embedded in everyday journeys: travel involves ticket booking, international payments, and insurance; shopping is linked to installment plans, cashback, and budget management; while Tet brings family spending, gifting, and saving needs. Visa data for 2026 shows that 76% of Vietnamese consumers shop online 2–3 times per month, up 19 percentage points from 2024; 56% own a multi-currency card and 34% have used one.
This shows that financial behavior is becoming closely connected to everyday needs rather than taking place as a separate journey. Customers expect financial solutions to appear naturally, at the right time, and in a way that fits the context they are in.
II. THE CHALLENGE: WHEN BRANDS NEED TO MOVE BEYOND THE PROMOTION BATTLE
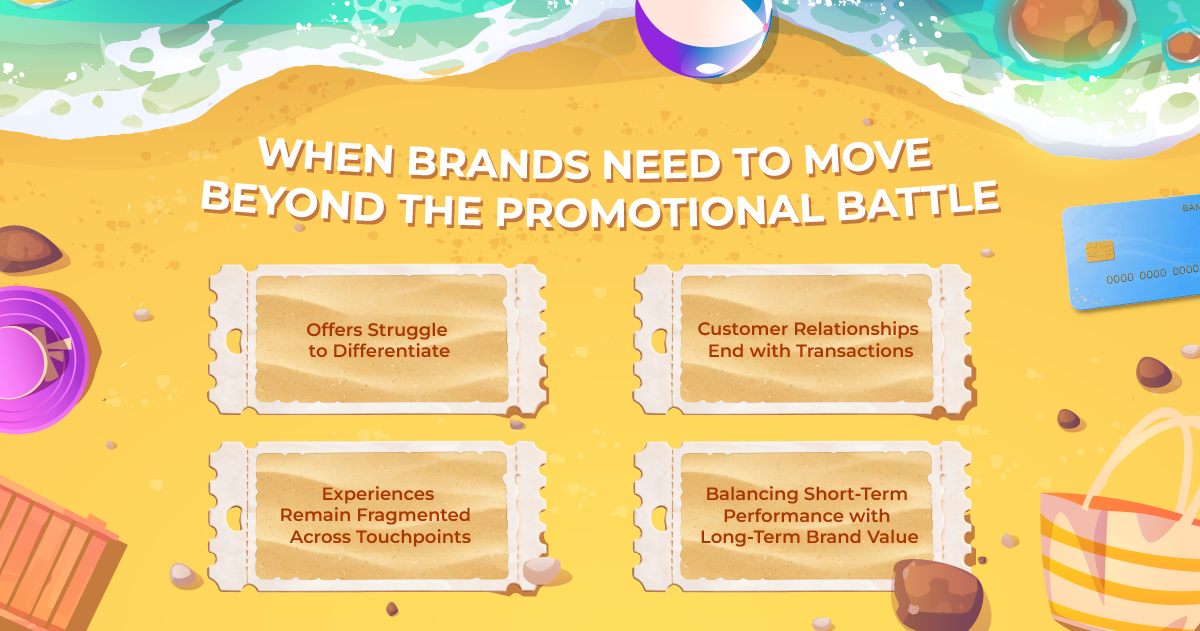
When Brands need to move beyond the promotional battle
1. Promotions are becoming less effective at creating brand differentiation
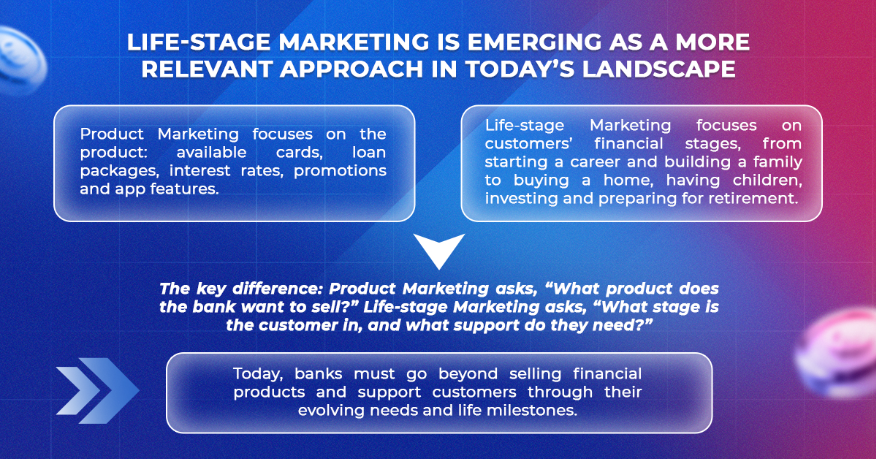
During the holiday season, cashback, vouchers, refunds, annual-fee waivers, and gifts for new cardholders have almost become the “common language” of the Bank – Finance sector. As promotion mechanics become increasingly similar, customers are more likely to compare brands based on immediate benefits rather than brand value or the overall experience.
The issue is not that promotions have stopped working, but that their ability to create differentiation is declining. If the only reason to choose a brand is a higher cashback rate, customers can just as easily switch when a competitor makes a more attractive offer. Brands can therefore be pulled into a cycle of rising promotional costs, while Brand Recall, Brand Preference, and Loyalty fail to grow at the same pace.
2. Customer relationships can easily stop at the transaction level
Many holiday campaigns still focus on short-term objectives such as opening cards, increasing transactions, activating payments, or driving voucher usage. This approach can generate quick results, but it can also reduce the brand experience to a single action.
Customers may open a card for a gift, pay for cashback, or use an app for a promotion, but once that motivation disappears, engagement may not continue. If each campaign only solves for one transaction, the relationship from acquisition to engagement, retention, and cross-sell becomes difficult to sustain.
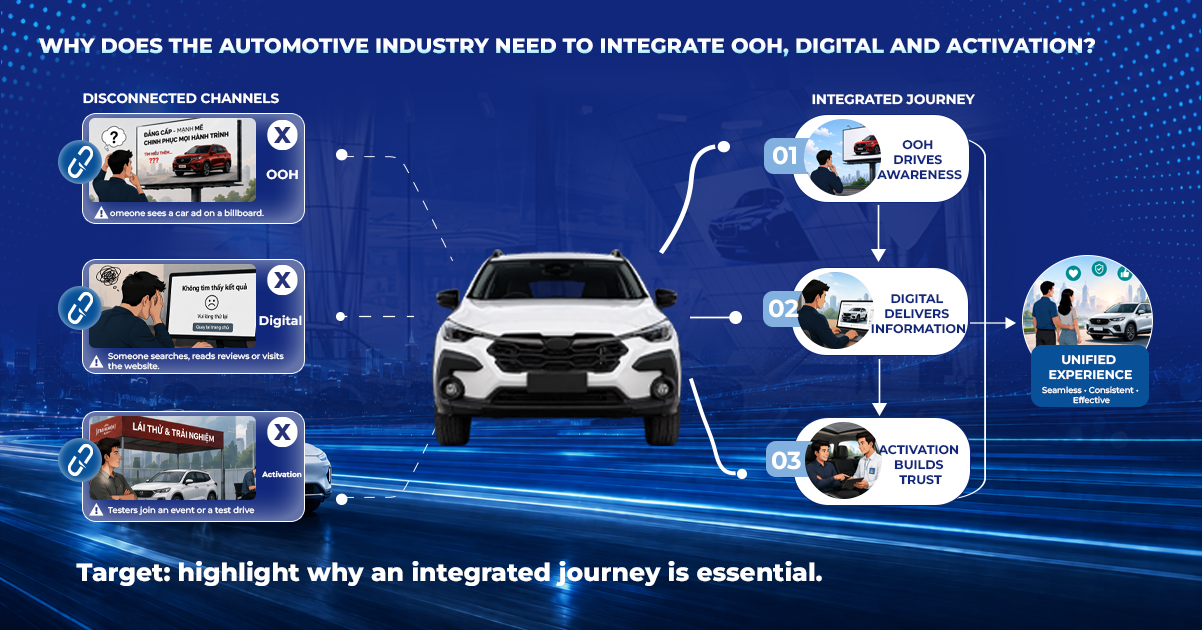
3. Customer experience remains fragmented across touchpoints
Today’s financial journey spans multiple touchpoints such as Social, Partner, App, Payment, CRM, and Loyalty. However, being present across multiple channels does not automatically create a seamless experience.
When channels operate independently, customers can encounter inconsistent messages, irrelevant offers, or repetitive actions. Disconnected data also makes it difficult for brands to understand where customers are in the journey and what they may need next. More touchpoints do not necessarily mean a more connected experience.
4. The tension between short-term performance and long-term brand value
The holiday season often comes with strong pressure on transactions, customer acquisition and conversion, new card openings, or GMV, making brands more likely to prioritize tactics that trigger immediate action.
However, if brands optimize only for the short term, they may face high promotion costs, low repeat rates, or a user base that is active only when incentives are available. A campaign that achieves transaction KPIs does not necessarily build stronger Brand Preference, Trust, or long-term customer value.
III. HOLIDAY 2026 STRATEGIC TRENDS FOR BANK – FINANCE
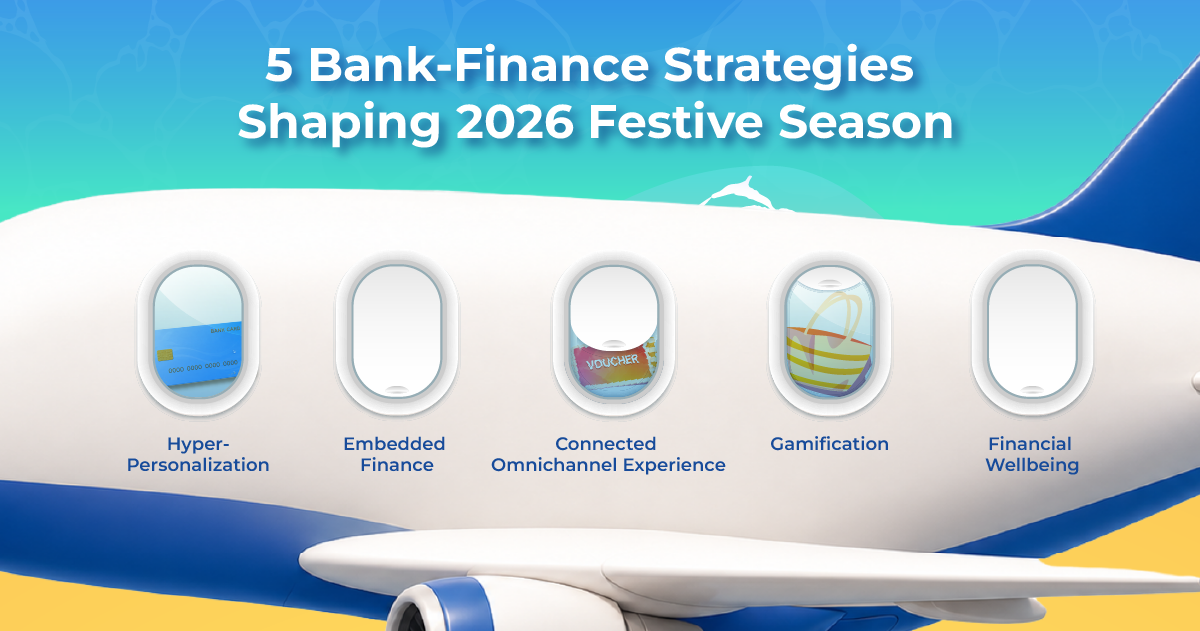
5 Bank – Finance strategies shaping 2026 Festive season
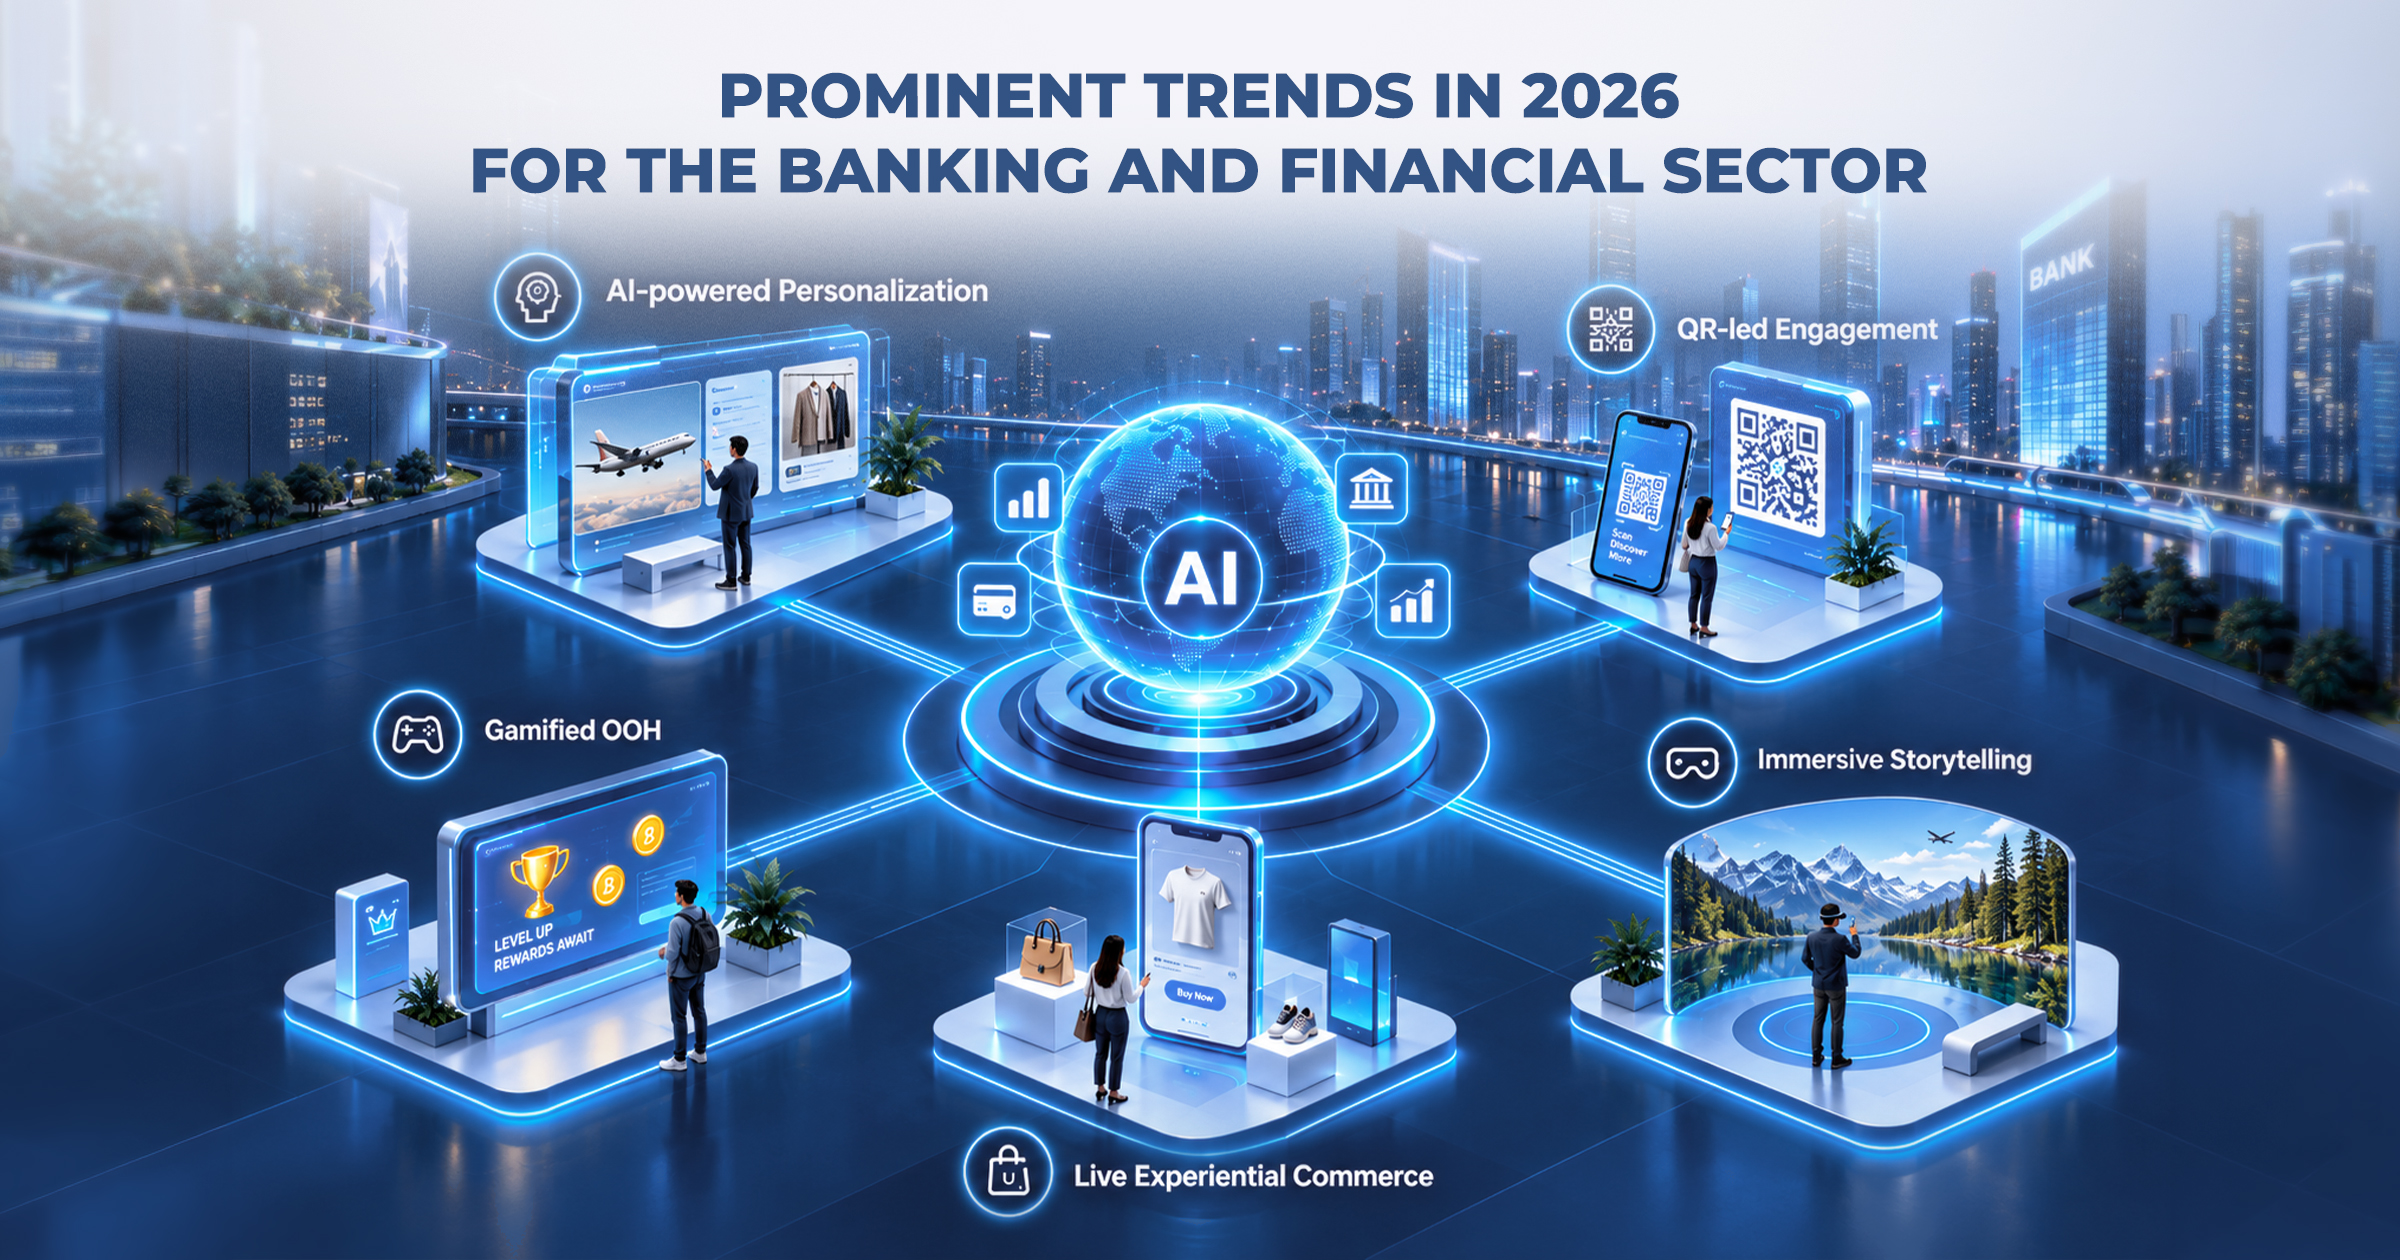
1. Hyper-Personalization: Personalizing experiences for each customer
Hyper-Personalization goes deeper than traditional Personalization. Instead of relying mainly on age, gender, location, or transaction history, it uses multiple layers of data to understand who the customer is, what situation they are in, what they need, and what action is most relevant at that moment.
For Bank – Finance, the same product can carry different meanings for different customers. A credit card can be a travel-points tool for a frequent traveler, an installment solution for someone making a major purchase, or a spending-management tool for a young family. Personalization therefore should not stop at “recommending the right product”; it should recommend the right value of that product in the right usage context.
Case study: Bancolombia x Dynamic Yield
Case study: Bancolombia x Dynamic Yield
a. Market context
Amid a major shift toward digital transactions and a base of more than 10.6 million users, Bancolombia faced a mass-content distribution problem that overloaded customers with information and reduced engagement. To build long-term relationships through personalization at scale, the bank leveraged real-time behavioral data across digital channels and continuously adjusted experiences, products, and messages based on each individual’s level of interest and actual needs.
b. Customer needs
Customers did not simply want more products or more offers; they wanted to quickly see options that matched their real needs. The bank already had extensive behavioral data, but the traditional Digital experience did not fully reflect these signals. Bancolombia therefore moved from relatively static segmentation to real-time product affinity recognition, allowing it to understand what customers were currently interested in and what needs might come next.
c. Strategic idea
Bancolombia built the experience around one principle: “let the content adapt to the customer” rather than forcing customers to adapt to a fixed campaign. The brand shifted from promotion-led, starting with an offer and then finding people to distribute it to, toward experience-led: identifying needs, personalizing the experience, and then presenting the right offer. Promotion therefore became part of a journey driven by actual customer interest instead of the center of the campaign.
d. How the brand executed it
Bancolombia used Dynamic Yield to build Affinity Profiles from real-time behavior, personalizing banners, landing pages, content, and offers for different need states. Personalization was expanded from pre-login and post-login experiences to the Tu360Compras ecosystem, connecting multiple Digital touchpoints. First-party data was combined with decisioning technology to automatically select the most relevant experience, while social proof increased trust and encouraged discovery of less familiar products.
e. Results
The personalization program increased CTR by as much as 1,000% at certain points, lifted average time on website by 66%, and increased engagement with selected product groups by 428.8%. On Tu360Compras, offers triggered by customer interest increased conversion by 18%. More importantly, Bancolombia strengthened its image as a bank that understands customers and turns data into relevant experiences, rather than competing only through products or promotions.
2. Embedded Finance: Integrating finance into the consumer journey
Embedded Finance brings services such as payments, installments, insurance, or loyalty directly into the consumer journey instead of keeping them as separate steps. Customers do not necessarily begin with a need to open a card or take out a loan; they begin with life goals such as shopping, travel, entertainment, or preparing for family needs.
For Bank – Finance, this means appearing at the exact moment a need occurs: integrating into the checkout step during shopping; connecting international payments, insurance, and travel offers; or linking financial services with tickets, membership, or exclusive entertainment benefits. Financial products then become a natural part of the experience instead of having to seek customers out separately.
Case study: Fresha Capital x Adyen
Case study: Fresha Capital x Adyen
a. Market context
The Beauty & Wellness industry continues to face strong cash-flow pressure. According to Adyen, 67% of businesses in the sector regularly experience cash flow issues, while 77% could not continue operating for more than three weeks without receiving payment revenue. Traditional lending processes, meanwhile, involve significant paperwork and long approval times. Fresha, a platform serving more than 140,000 businesses and 450,000 professionals, saw an opportunity to embed access to capital directly into its existing ecosystem.
b. Customer needs
Salons and spas need capital that is fast, flexible, and available at the right moment, rather than having to go through a separate lending process. 86% of Beauty & Wellness businesses said limited access to capital could lead to staff cuts or closure, while 37% wanted to receive financial support directly from the software platform they already use. Fresha Capital addressed this need through pre-approved offers and direct disbursement into Fresha Wallet.
c. Strategic idea
Fresha evolved from a management and payment platform into an ecosystem capable of delivering financial services directly within the business operating journey. Capital was not sold as a separate lending product. Instead, it appeared at the moment of need, when a business required funding to maintain or expand operations. This is Embedded Finance in its true sense: finance becoming part of the experience rather than a separate journey.
d. How the brand executed it
Fresha integrated Adyen Capital directly into its digital wallet. Eligible businesses received pre-approved offers based on payment history, could access funding quickly, and repaid automatically as a percentage of daily revenue. Fresha controlled the user experience, while Adyen handled the lending infrastructure, compliance, and credit risk. The solution was rolled out across 7 markets in only around 3 weeks.
e. Results
Within just a few weeks of launch, Fresha had provided more than USD 8 million in capital; 89% of customers who borrowed once returned to use Capital a second time. One business that used the funding for a December marketing campaign recorded a 22% increase in gift card sales, showing how Embedded Finance can directly help businesses capture peak-season demand.
3. Connected Omnichannel Experience: Connecting touchpoints into one seamless journey
Connected Omnichannel Experience is not simply about being present across multiple channels. It is about connecting data, content, and actions to create one continuous journey. Social Media creates demand, Application continues the personalized experience, Payment captures behavior, Partner Ecosystem expands consumption contexts, while CRM and Loyalty sustain the relationship after the transaction.
For Bank – Finance, this matters because customer journeys are often fragmented. A customer may first see an offer on Social, explore it in the App, use it with a partner, pay by card, and then receive follow-up communication through CRM. If these touchpoints are not connected, the experience can become repetitive, inconsistent, and less relevant.
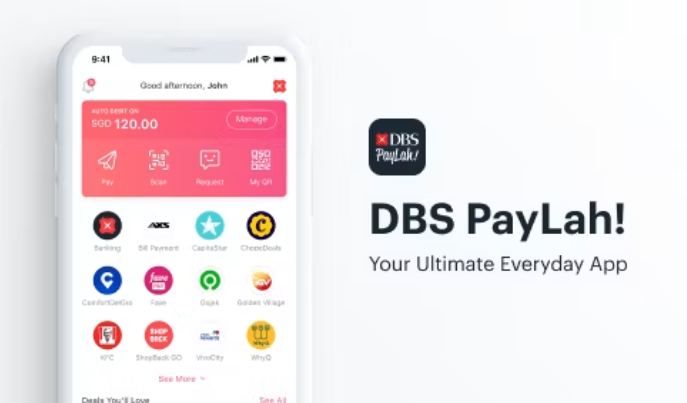
Case study: DBS PayLah! – Connected Everyday Banking Experience
Case study: DBS PayLah! – Connected Everyday Banking Experience
a. Market context
As digital payments became mainstream in Singapore, DBS’s challenge was no longer simply getting users to download the app, but keeping PayLah! relevant in everyday life. When customers had to use multiple touchpoints for payments, cards, offers, and loyalty, DBS saw an opportunity to bring them together into an “everyday banking” ecosystem that connected financial transactions with shopping, dining, transport, and lifestyle.
b. Customer needs
Customers wanted to make payments, check spending, receive offers, and use reward points without switching between multiple platforms. The previous experience was fragmented across PayLah!, DBS/POSB cards, and a separate rewards app. The core need was therefore not simply more offers, but a convenient experience where benefits and financial behavior could be managed in one place.
c. Strategic idea
DBS repositioned PayLah! from a mobile wallet into an everyday app, connecting Payment, Rewards, and Lifestyle within a single journey. Instead of using individual cashback programs to stimulate one-off transactions, the bank created a loop of payment – benefit – spending tracking – reward redemption – continued ecosystem usage. Promotion became part of a long-term experience rather than the end point of a campaign.
d. How the brand executed it
DBS integrated rewards into PayLah! so customers could view spending history, receive personalized offers, and redeem rewards within the same app, while also linking DBS/POSB cards to the payment platform. The ecosystem expanded through partnership with yuu Rewards, supermarket, F&B, transport, and a wide range of lifestyle merchants, connecting the experience from App to Payment and then Loyalty at the point of sale. yuu enables customers to earn and redeem the same loyalty currency across more than 1,000 locations, while the DBS yuu card adds another rewards layer across the partner ecosystem.
e. Results
PayLah! surpassed 3 million users and processed more than 60% of QR transactions at hawker centres; by 2026, more than 5 million customers were using DBS/POSB cards and/or PayLah! to receive rewards across more than 850 merchant touchpoints. Customers saved a combined SGD 13.7 million through cashback and rewards in the previous year; grocery spending on everyday card portfolios increased 7%, while transport spending increased 5%. This model strengthened DBS’s positioning from a transactional bank into a brand that is regularly present in everyday life.
4. Gamification & Interactive Engagement: Turning financial transactions into participatory experiences
Gamification & Interactive Engagement brings game mechanics and interactive elements into the financial journey, turning customers from passive transaction makers into active participants. Instead of simply receiving cashback or a voucher after payment, users can complete missions, collect points, unlock rewards, or join challenges tied directly to their financial behaviors.
This trend makes activities such as payments, saving, card usage, or spending management more approachable and motivating. Gamification also creates repeated interaction points, encouraging customers to return to the App or ecosystem more frequently rather than only when they need to make a transaction.
Case study: ACB – “Mã đáo phát tài” 2026
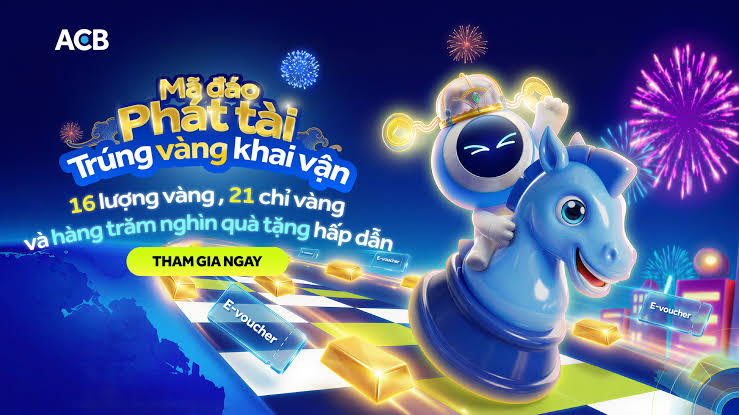
Case study: ACB – “Mã đáo phát tài” 2026
a. Market context
Tet is a period when banks simultaneously launch offers to stimulate deposits, payments, and card usage, making promotion alone increasingly difficult to differentiate. ACB therefore introduced game mechanics into everyday transactions, turning financial activity into a Tet experience with entertainment and interaction built in.
b. Customer needs
During Tet, customers still make deposits, pay, shop, and use cards, but financial offers can easily feel similar across brands. ACB tapped into the desire for luck, entertainment, and instant rewards, turning transactions into activities that gave customers a reason to return rather than simply receive cashback after payment.
c. Strategic idea
ACB built “Mã đáo phát tài” around a loop of transaction – game turn – interaction – reward – return. Gamification did not exist as a separate mini game; it was directly linked to banking behavior, giving each transaction an added layer of experience and another reason to continue using ACB ONE.
d. How the brand executed it
Customers received game turns when completing eligible transactions at branches or on ACB ONE, such as making deposits, purchasing certificates of deposit, making payments, shopping, or using credit cards. In the app, users could roll dice, collect gold coins, and join “Săn thần mã,” with rewards including gold, E-vouchers, and ACB Rewards. Gamification therefore connected directly with Transaction, App Engagement, and Loyalty.
e. Results
The online program alone recorded more than 2 million transactions that earned game turns and more than 600,000 participating customers. At branches, ACB also recorded more than 8,000 participants. This shows that gamification created substantial interaction at scale around banking behaviors that would otherwise feel routine.
5. Financial Wellbeing: From encouraging spending to helping customers spend better
Financial Wellbeing reflects a shift in the role of financial brands: from primarily driving transactions to helping customers manage money better and make more appropriate financial decisions. Instead of appearing only through cashback, vouchers, or card offers, brands can support customers through Spending Insight, Budget Planning, Smart Recommendation, or Spending Alert.
At the core of Financial Wellbeing is the use of financial data to create practical value. Transaction data is not only used for cross-selling, but also to provide recommendations that fit each customer’s financial capacity and goals, making the brand more useful in everyday life while strengthening Trust and Loyalty.
Case study: MoMo – “Quản Lý Chi Tiêu” (Expense Management)
Case study: MoMo – “Quản Lý Chi Tiêu” (Expense Management)
a. Market context
As digital payments become more common, Vietnamese users make many transactions every day but often struggle to see the overall picture of their cash flow. According to MoMo, more than 90% of users have a need for personal financial management, yet only around 8% manage their finances systematically. MoMo’s opportunity was to leverage existing transaction data to expand its role from a payment platform into a tool that supports personal financial management.
b. Customer needs
Users want to understand where their money goes, control budgets, and avoid overspending, but manual tracking is time-consuming and difficult to maintain. The gap lies in the fact that transaction data already exists, but has not yet been translated into easy-to-understand insight that supports decision-making.
c. Strategic idea
Instead of only encouraging more payments through vouchers and cashback, MoMo turned transaction data into an expense-management assistant. The objective shifted from driving transactions to helping users understand their financial behavior, control budgets, and build better money-management habits.
d. How the brand executed it
MoMo uses AI to automatically capture and categorize transactions, compile weekly/monthly reports, allow users to set budgets by category, and send alerts when they are close to or have exceeded their limits. The AI assistant can also answer questions about spending, support goal-setting, and suggest ways to manage money. Everything is integrated directly into the MoMo ecosystem, so users do not need to switch to a separate financial-management app.
e. Results
According to MoMo, the Quản Lý Chi Tiêu feature has been used by more than 3 million users to track monthly income and expenses. This scale shows that the need for personal financial management is real and that the solution has achieved significant adoption. More importantly, MoMo has expanded its role from a payment platform into a tool that helps users track, understand, and manage cash flow more effectively.
KEY TAKEAWAY
All five trends show that Holiday 2026 in Bank – Finance is shifting from simply pushing transactions toward creating more relevant customer experiences. Hyper-Personalization personalizes value, Embedded Finance places finance directly within the moment of need, Connected Omnichannel Experience connects the journey, Gamification increases interaction and repeat usage, while Financial Wellbeing helps customers manage money better. The focus is therefore no longer just on promotions, but on creating value at the right moment and sustaining long-term relationships.
IV. PERSPECTIVE & RECOMMENDATIONS FROM NOVAON DIGITAL
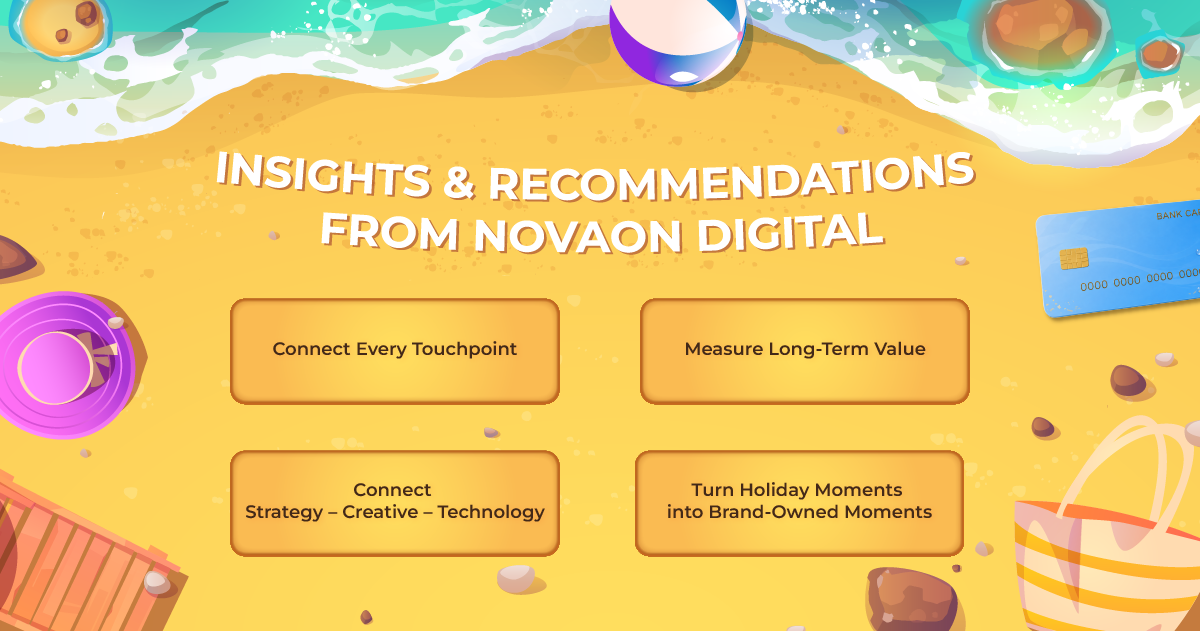
Insights & Recommendations from Novaon Digital
1. Shift from bigger promotions to the right value at the right time
During the holiday season, increasing cashback or vouchers can drive short-term results, but it is difficult to create sustainable differentiation this way. Brands should begin with real needs such as year-end shopping, travel, gifting, Tet preparation, or family spending, then design benefits that fit each context. The value of an offer therefore lies not only in the size of the discount, but in how relevant it is to customer needs.
2. Connect touchpoints to extend the customer journey
A transaction should not be the end point of a campaign. Social, App, Payment, Partner, CRM, and Loyalty need to be connected into one continuous journey, where data from one touchpoint supports the next experience. After a card is opened, a payment is made, or an offer is redeemed, brands should continue creating reasons for customers to return through content, benefits, and personalized offers.
3. Expand measurement from short-term conversion to long-term value
Transaction, Acquisition, and Conversion remain important, but they are not enough to reflect the quality of growth. Brands should also track Repeat Usage, Engagement, Retention, Cross-sell, and the ability to retain customers after the campaign to assess whether growth is coming only from short-term promotions or is genuinely creating long-term value for the brand-customer relationship.
4. From strategy to execution: a connected experience system is required
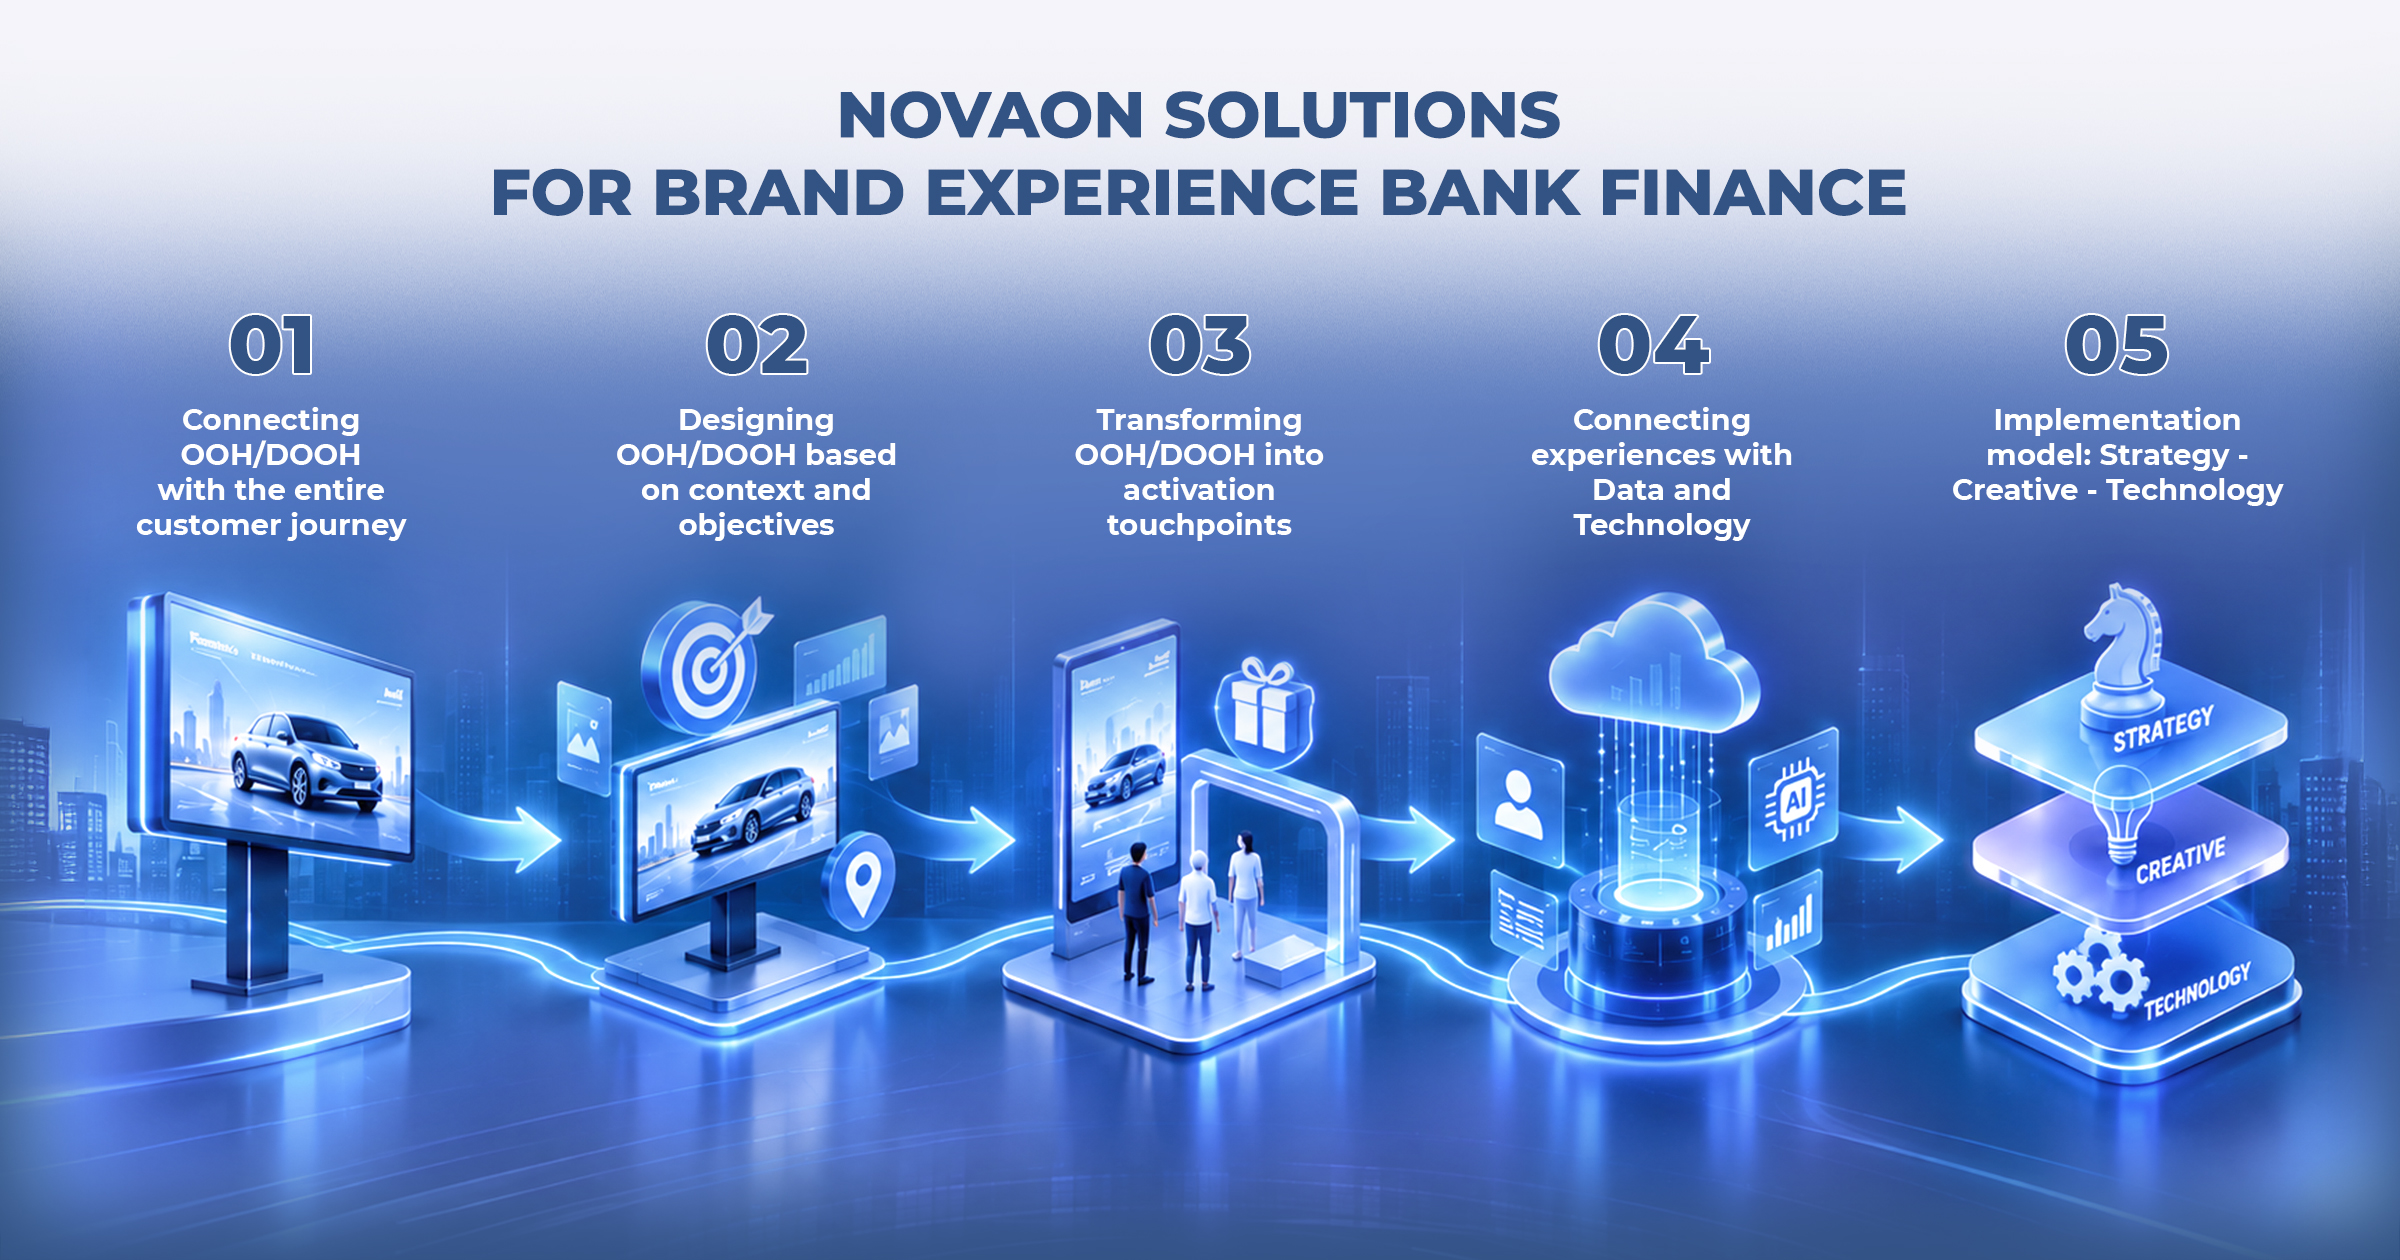
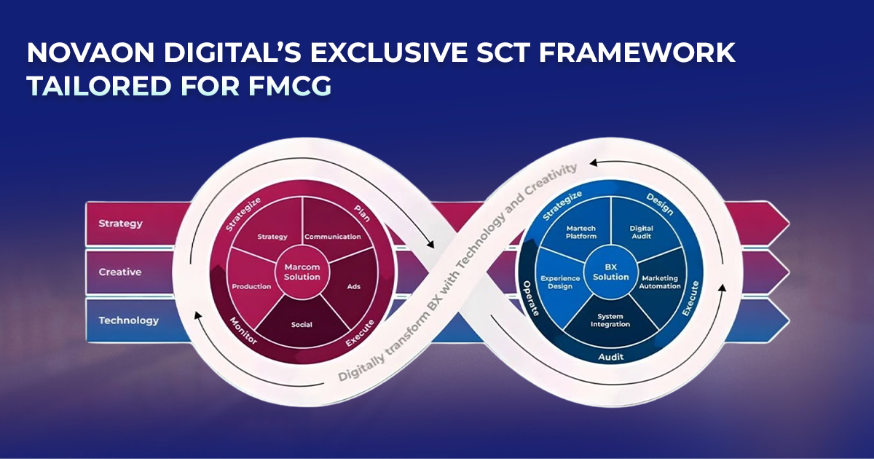
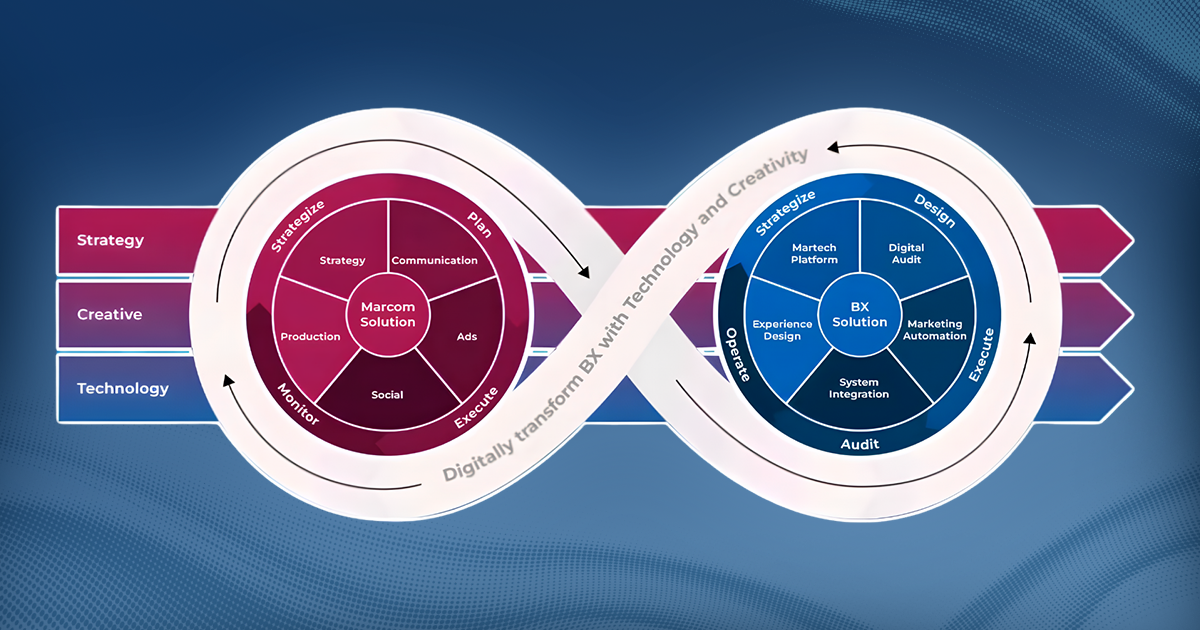
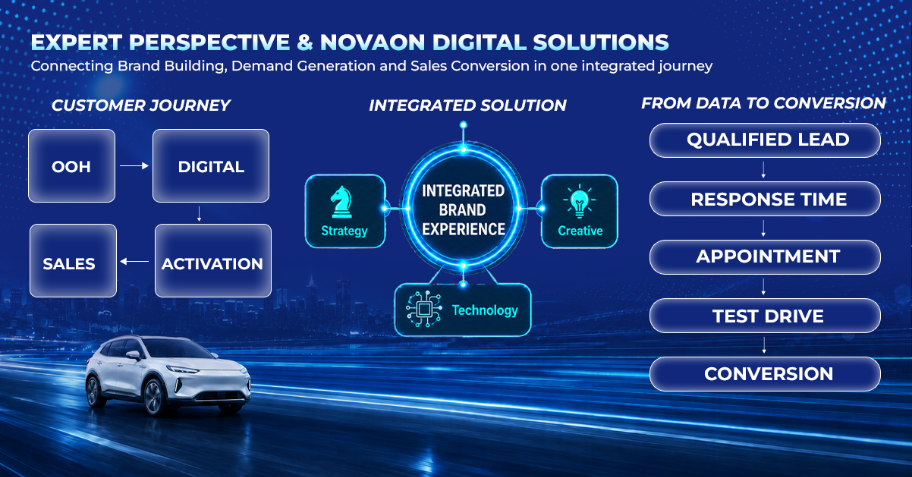
To ensure these directions do not remain only as ideas, brands need to build Brand Experience across three layers: Strategy – Creative – Technology. Strategy helps understand users, identify the right financial moments, and design the customer journey; Creative turns Insight into Big Idea, Storytelling, and memorable experiences; Technology connects touchpoints, personalization, interaction, and data so the journey can be sustained end to end.
For Holiday Marketing, this approach allows brands to do more than participate in the festive season with a short-term campaign. Over time, they can own a Holiday Moment and turn it into a Brand-owned Moment. This is also how Novaon Digital connects Media, Activation, Digital, and Martech within one system, aiming to deliver the right experience to the right person, at the right time, through the right touchpoint – ultimately creating Engagement – Conversion – Loyalty – Growth.
V. CONCLUSION
Holiday 2026 shows a clear shift in how Bank – Finance brands compete. As cashback, vouchers, and other promotions become increasingly common and easy to replicate, advantage no longer comes from who “gives more,” but from who understands customers more deeply and appears at the exact moment they genuinely need support.
This also means that brand objectives need to go beyond a single transaction. From Hyper-Personalization and Embedded Finance to Connected Omnichannel Experience, Gamification, and Financial Wellbeing, the common goal is to extend the customer relationship and turn every touchpoint into part of a consistent and valuable experience.
Therefore, in Holiday 2026, the winning financial brand will not be the one offering the biggest promotion, but the one that designs an experience that makes customers feel understood, supported, and gives them a reason to stay for the long term.
Cre: Brands Vietnam